Quick Facts About the Buying and Selling Marketplace
- In October, the average sale price of a new car reached an all-time record.
- Used car prices dipped slightly last month but are likely to rise again soon.
- The good news? It hasn’t been this easy to qualify for a new car loan since April 2015.
New cars have never been more expensive than they are right now.
The average American new car buyer paid $51,109 in October — an all-time record. Longstanding patterns mean we’re likely to eclipse that record in November, and surpass it again in December.
Strangely, prices aren’t rising faster than they do in a typical year. October’s average was 2.1% higher than a year earlier. Historically, 3% year-over-year price increases are normal.
But that means little to the average new car shopper, who is just trying to secure safe and reliable transportation without torpedoing their budget.
Consumers also have more control over prices than the headlines might suggest. Much of the price growth comes from the choices car shoppers make. Luxury cars, higher-end trims of mainstream cars, and pickup trucks with expensive option packages drive up the average.
Savvy shoppers can still find a quality car for much less.
Used car prices, meanwhile, rose back to near pandemic-era highs.
We’ll explain what to expect when buying a new or used car, or selling or trading one in, and why it might make sense to act quickly.
- What New Car Shoppers Can Expect
- Each Automaker Is Responding Differently
- What Used Car Shoppers Can Expect
- Older, Less Expensive Cars Harder to Find
- Automakers Build More Expensive Cars
- How to Buy a Car Right Now
- Selling a Car Right Now
- Trading in a Car Right Now
- Looking Ahead
- Tips for Buying a Vehicle Right Now
What New Car Shoppers Can Expect
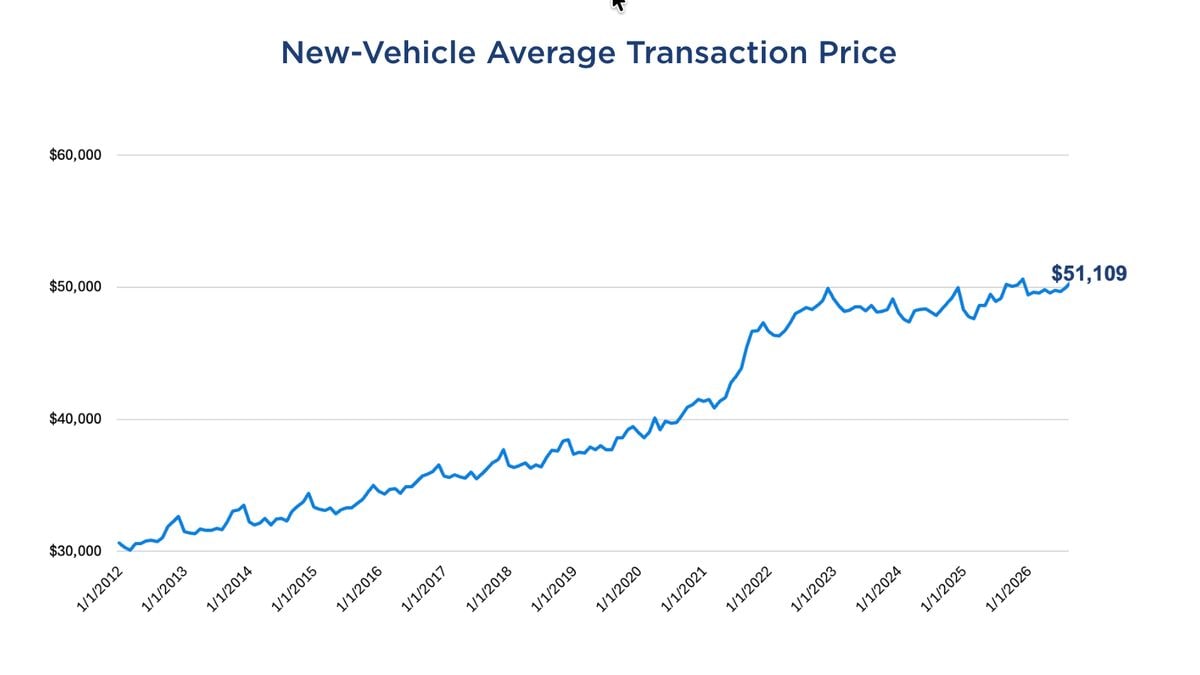
The average new car buyer paid $51,109 in October — the highest figure ever.
It sounds alarming. But three factors put the figure into perspective.
First, price growth is relatively slow right now. Over the last decade, prices have tended to rise about 3% year over year. October’s figure was just 2.1% higher than a year earlier.
Second, prices typically tick up late in the year as cars from the new model year reach dealer lots.
Third, consumer choices play a big role in the average. Shoppers can keep costs down by choosing less expensive vehicles.
Americans continue to spend more than they need to on transportation. Luxury vehicles have made up nearly 20% of the market for much of the past year, and buyers often choose luxurious, well-equipped trim levels even on affordable cars. All major gas-powered full-size pickups, for instance, have starting prices in the low $40,000 range. But the average full-size truck buyer spent more than $67,000 last month.
By segment, the average transaction price story is more nuanced:
- Midsize SUV: $50,570, up 1.9% year over year.
- Compact SUV: $37,895, up 4.3% year over year.
- Full-size pickup truck: $67,912, up 1.4% year over year.
- Subcompact SUV: $31,333, up 1.9% year over year.
- Compact car: $28,030, up 3.4% year over year.
While it’s always tempting to spring for the best model available, it’s still possible to save money. Try to buy only as much vehicle as you really need, and be open to brands with more supply on dealers’ lots.
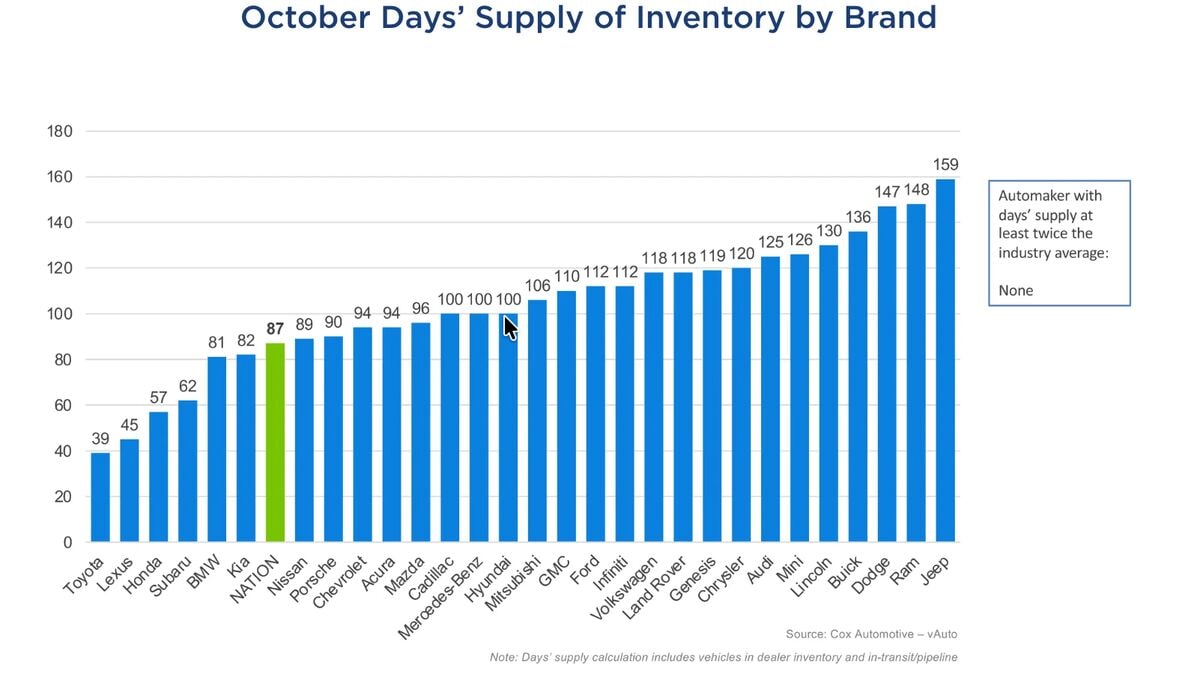
Dealers generally aim to keep a 60-day supply of new cars on the lot and up to 15 days on order, for a total supply of 75 days. The average automaker was well over that target last month. But an average can be made up of extremes — some automakers were well above that level, which could mean more deals and lower prices. You have more negotiating leverage at brands like Jeep, Dodge, and Ram this month. You have very little at Toyota, Lexus, or Honda.
Each Automaker Is Responding Differently
Since last April, big swings in tariff policy have complicated decisions for automakers and dealers. Each automaker has responded to tariffs differently. As long as the tariffs remain, those responses will likely continue to change.
Imported vehicles have seen the largest price increases, estimated at $5,000 to $8,900 per vehicle. Domestic vehicles are not exempt from the tariff burden. Because of tariffs on imported materials, such as steel and aluminum, the cost of domestic vehicles has increased by an estimated $1,600 to $2,000 per vehicle.
RELATED: How Each Automaker Is Responding to Tariffs
Automakers have absorbed some of the cost of tariffs so far. They might even raise the price of one car to help pay for the tariff costs associated with another model.
With so much shifting, your best tool for understanding local price changes is the Kelley Blue Book Fair Purchase Price, which we calculate using recent transactions for that vehicle in your area. We update each Fair Purchase Price weekly, showing you how tariffs and other market factors are affecting the prices of the specific vehicles you’re shopping for where you live.
Loan Conditions Continue to Improve
Prices are all that cash buyers need to worry about. However, few car shoppers pay cash. Most Americans borrow money to buy a new car.
On that front, the news is good — if you’re careful.
In October, lenders approved nearly 74% of all applications. Qualifying for a car loan was easier than it had been at any time since April 2015. The average down payment was just 13%.
There are, however, warning signs in the data. Nearly six in 10 buyers who trade in a vehicle carry negative equity from an old loan into their new loan. Additionally, almost a third of new loans stretch 72 months or longer — a move that lowers monthly payments but costs the borrower more in the long run. But qualifying is unlikely to get easier anytime soon.
Remember to shop for your loan based on its total cost, which can be found on the Truth in Lending Disclosure included in every loan offer by law. A lower monthly payment isn’t worth it if it costs you significantly more in the long run.
Rates look increasingly likely to worsen soon, with most observers now expecting the Federal Reserve to raise its benchmark interest rate this fall. Compare financing offers and focus on the total cost of borrowing rather than the monthly payment alone.
What Used Car Shoppers Can Expect
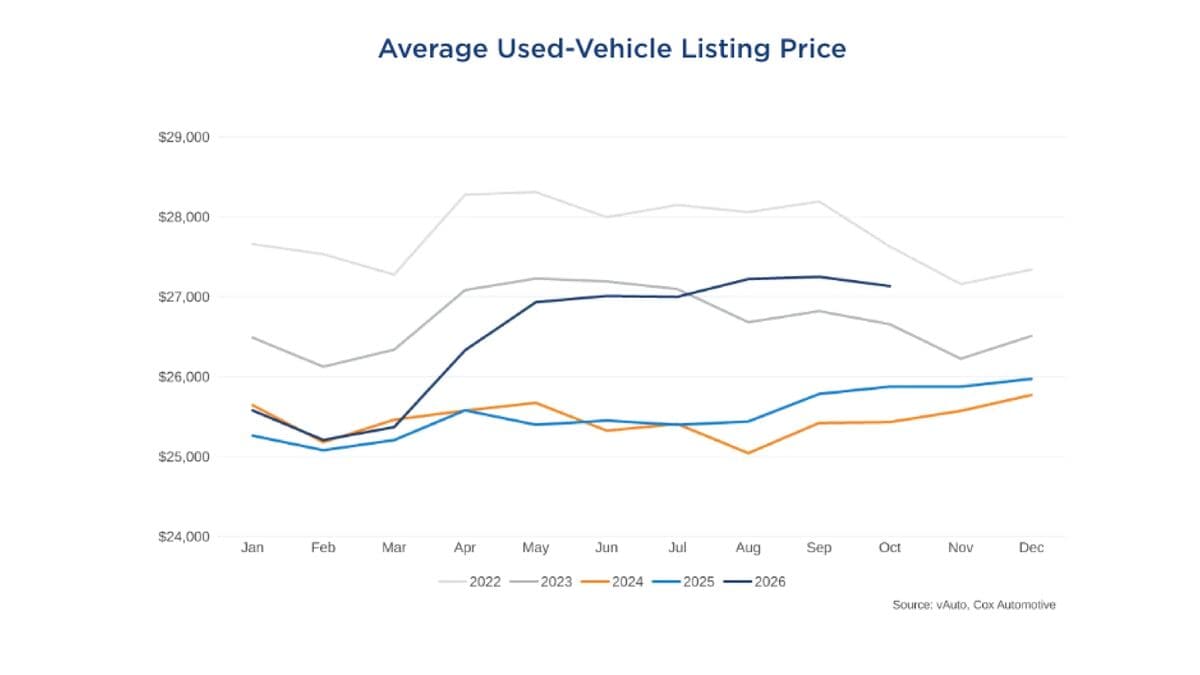
The average used car was listed for $27,133 in October — a decrease of $117 from September’s figure. That’s not likely the start of a downward trend.
To predict used car prices, we track the wholesale prices dealers pay at auction for used cars. Retail prices tend to follow wholesale prices with a lag of about six to eight weeks. Wholesale prices have been rising in recent weeks, meaning retail prices are likely to increase slightly in November and December.
Long-term trends are working against used car shoppers.
Americans are holding onto their cars much longer, and automakers have been producing fewer cars for several years. That means fewer used cars are available and prices are higher for the vehicles on dealers’ lots.
MORE: 1926: The Used Car Market Got a Pricing Foundation
Older, Less Expensive Cars Are Harder to Find
If you hope to find an older vehicle and your budget is less than $15,000, expect a limited selection. Dealers have few such vehicles in stock.
The tariff threat could also push used car prices higher. When new car prices rise, would-be new car shoppers head to used lots looking for something still in their price range. That additional demand reduces used vehicle inventory. Plus, Americans are holding onto their cars longer than ever. The average vehicle on American roads is 12.8 years old. Automakers also produced fewer cars for several years after the 2008 recession, leaving fewer higher-mileage, older vehicles available for sale.
Once again, Ford, Chevrolet, Toyota, Honda, and Nissan were the top-selling brands, accounting for nearly 50% of all used vehicles sold.
Automakers Build More Expensive Cars
If you haven’t been car shopping in a while, the cars available may surprise you.
In recent years, inexpensive cars have grown scarce. In model year 2017, automakers offered 75 models priced under $30,000. In model year 2027, they’ll offer just 13. Below $25,000? Just six.
At the other end of the scale, the trend is reversed. In 2017, automakers sold 42 models with a starting price over $70,000. This model year, they’ll offer 81.
Dealers are pushing back, telling automakers they need more mainstream cars to sell, but correcting the problem will take time.
How to Buy a Car Right Now
New car prices are about $10,000 higher than before the COVID-19 pandemic. That’s when the average transaction price for new vehicles was just under $41,000. However, with all the technological advances and offerings, your next car will likely last longer and help you drive safer than ever.
RELATED: Buying Older, Used Cars in 2026
Vehicle quality studies repeatedly show that today’s new cars suffer fewer problems than those from just a few years earlier. Buyers of higher-priced used cars will likely see those vehicles stay on the road even longer. The same goes for those buying new ones.
With most automakers now building such durable cars, they compete by adding more high-tech features. Features like adaptive cruise control and Apple CarPlay are now more common than ever on entry-level vehicles. Read on for our tips on buying a car right now.
How to Leverage Incentives to Buy a New Car
Last month, incentives comprised about 6.8% of the average deal. To learn how to take advantage of incentives, read about our monthly best car deals for dealer or manufacturer offers, including cash back and lower interest rates when financing your next vehicle.
RELATED: How to Buy a New Car in 10 Steps
Selling a Car Right Now
Few of us can sell a car without needing to buy a replacement. If you can sell now, what are you waiting for? You could get more for your vehicle if it’s in high demand, and that’s excellent news. The best way to get the most money for your used car is to sell it privately. But if you don’t want the hassle, there is still an opportunity to sell to a dealership.
Trading in a Car Right Now
The ongoing shortage of used cars will linger for years. As a result, you’ll likely still see respectable offers for your used car this month.
Shopping around for a decent price for your trade-in is still a good idea. Each dealership tries to keep a balance of vehicles on its lot. Sometimes, the one you want to buy from doesn’t need your trade-in desperately, but a competitor does.
Research your vehicle’s Kelley Blue Book value, then call several local dealerships to see what they’ll offer you for it. Or try our Instant Cash Offer tool, which brings you deals from various dealerships without obligation. You can choose your preferred offer or use it to negotiate with others.
Is Trading in Your Vehicle a Good Idea?
Possibly. You could get more money than usual if your vehicle is in high demand. That can help defray the costs of buying a new or used car. However, if your vehicle is not in high demand, you can expect to get close to the Kelley Blue Book value. Use Kelley Blue Book’s car valuation tool to find out the value of your current car.
Can You Trade in a Vehicle That’s Not Paid Off?
Yes. Whether you have paid off your car or not, you can still trade it in. However, a car depreciates as you drive it away from the dealership. It’s best to take stock of how much equity you carry in the vehicle. Take the difference between the car’s current market value and what you owe to figure that out. Read our story on selling a car.
Looking Ahead
New car prices tend to rise in late summer and early fall as cars from the next model year start to appear on dealer lots. Automakers will eventually have to address the yawning gap at the low-cost end of the car market. But they’re being conservative with their business decisions now, with few willing to take the risk of designing cheaper cars when the expensive ones are selling so well.
Used car prices, barring any unusual market disruptions, should increase only slightly.
If you need a new car soon, it might make sense to act now before interest rates rise.
RELATED: 10 Best Used Car Deals
Tips for Buying a Vehicle Right Now
If you shop right now, we recommend a few strategies to help you find the right new or used car that fits your budget.
- Expand your search. Widen your search to a broader geographic area because you could find a better deal or the used car you want outside your immediate area.
- Stay patient. Call dealerships to see what’s in stock for those high-demand vehicles. Leave a refundable deposit if you want first dibs.
- Buy a less expensive model. With higher car loan interest rates, consider buying a cheaper model instead of a more expensive one in the lineup you’re considering. Understand how much you can afford.
- Look for deals. Make sure to research car deals to find what works best for you. It may involve contacting or visiting several dealerships as you search for the right fit.
- Weigh your options. Don’t just look for a car; search for the best interest rates from banks or credit unions. Also, shop for insurance rates before the deal to know what it will cost to insure your desired vehicle. Then weigh all your options, including financing incentives and deals at the dealership, if that’s where you buy your next vehicle. You may also find that the prices of some newer-model used vehicles are almost the same as those of new cars. Keep all your options open during your search.
- Avoid dealer markups. If you see a markup (sometimes called a “market adjustment”) on your final invoice, ask the dealer to remove it. If they refuse, shop at another dealership. Markups were more prevalent during the COVID-19 pandemic. However, dealers still mark up some vehicles that are in short supply.
- Question all add-ons. If your sales summary includes entries like “window tint,” “fabric protection,” “carpeted floor mats,” and other add-ons you didn’t request, ask the dealer to remove those line items from your invoice. Many dealers tack on these extras to make quick profits.
It may make more sense to keep your existing car for another year or two. If you must buy, be prepared to take excellent care of your next car to keep it running for a long time. Visit our Car Affordability Information Center for curated articles to help you make smart, budget-friendly decisions.
Editor’s Note: We have updated this article since its initial publication.