Quick Facts About the Buying and Selling Marketplace
- In August 2026, the average sale price of a new car drifted over $50,000 for the first time this year.
- Used car prices have risen to near their pandemic-era highs again.
- The good news? It hasn’t been this easy to qualify for a new car loan since 2015.
New car prices and used car prices both rose last month, and both hit unfortunate milestones. The news, however, isn’t as bad as it seems.
The average new car transaction price crossed the $50,000 line for the first time in 2026. That sounds alarming, but prices are actually rising more slowly than they do in a normal year. Our new national normal just happens to sound particularly significant this month.
The average buyer paid 1.9% more this August than last August. By historical standards, that’s not bad — over the past decade, year-over-year growth has typically been closer to 3%.
Consumers also have more control over prices than the headlines might suggest. Much of the price growth comes from the choices car shoppers make. Luxury cars, luxurious trims of mainstream cars, and pickup trucks with expensive option packages drive the average higher.
Savvy shoppers can still find a quality car for much less.
Used cars, meanwhile, rose back to near 2022 levels.
We’ll explain what to expect when buying a new or used car, or selling or trading one in, and why it might make sense to act quickly.
- What New Car Shoppers Can Expect
- Each Automaker Is Responding Differently
- What Used Car Shoppers Can Expect
- Older, Less Expensive Cars Harder to Find
- Automakers Build More Expensive Cars
- How to Buy a Car Right Now
- Selling a Car Right Now
- Trading in a Car Right Now
- Looking Ahead
- Tips for Buying a Vehicle Right Now
What New Car Shoppers Can Expect
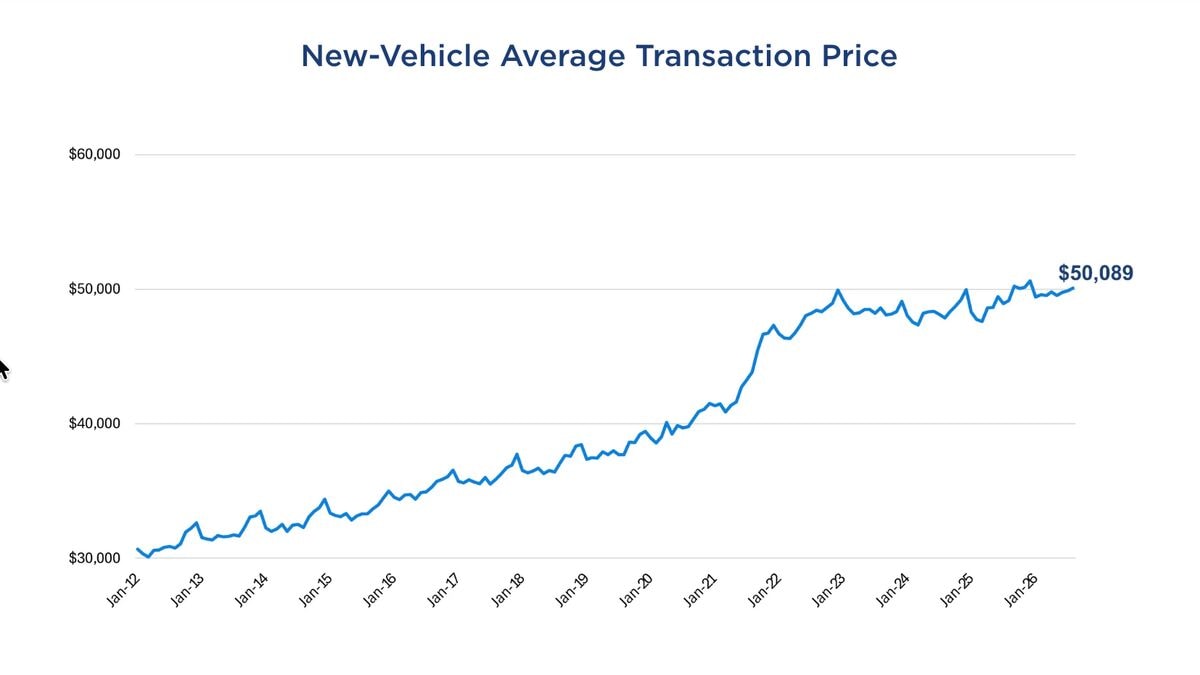
New car buyers paid an average of $50,089 in August. That’s the first time the figure has crossed the $50,000 threshhold since last December.
It sounds alarming. It’s not as significant as it seems for two reasons.
One is that actual price growth is relatively slow right now. Over the last decade, prices have tended to sit around 3 points higher each month than they were in the same month the year before. August’s figure is just 1.9% higher, year over year.
The other is that consumer choice plays a big role in the number, and you can choose a less expensive car.
Americans continue to spend more than they need to on transportation. Luxury vehicles have made up nearly 20% of the market for much of the past year, and buyers often choose luxurious, well-equipped trim levels even on reasonably affordable cars. All of the major gas-powered full-size pickups, for instance, have starting prices in the low $40,000 range. But the average full-size truck buyer spent more than $67,000 last month.
By segment, the story is more nuanced:
- Midsize SUV: average transaction price of $50,315, up 1.6% year over year
- Compact SUV: average transaction price of $37,722, up 1.1% year over year
- Full-size pickup truck: average transaction price of $67,446, up 2.1% year over year
- Subcompact SUV: average transaction price of $31,149, up 2.2% year over year
- Compact car: average transaction price of $27,997, up 2.9% year over year
While it’s always tempting to spring for the best model available, it’s still possible to save money. Try to choose only as much car as you really need, and be open to brands with more supply on dealers’ lots.
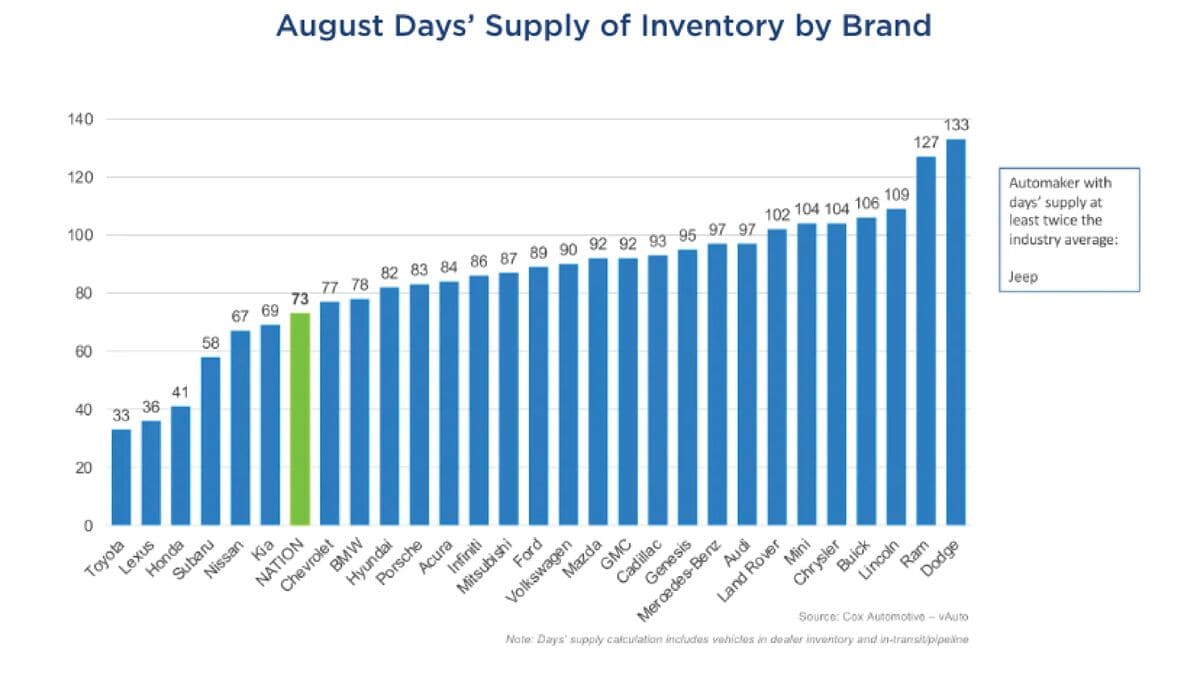
Dealers generally aim to keep a 60-day supply of new cars on the lot and up to 15 days on order. The average automaker was slightly below target last month. But an average can be made up of extremes — some automakers were well above that level, which could mean more deals and lower prices.
Each Automaker Is Responding Differently
Since last April, big swings in tariff policy have complicated decisions for automakers and dealers. Each automaker has responded to tariffs differently. As long as the tariffs remain, those responses will likely keep changing.
Imported vehicles have seen the largest price increases, estimated at $5,000 to $8,900 per vehicle. Domestic vehicles are not exempt from the tariff burden. Due to tariffs on imported materials, such as steel and aluminum, the cost of domestic vehicles has increased by $1,600 to $2,000 per vehicle.
RELATED: How Each Automaker Is Responding to Tariffs
Automakers have absorbed some of the cost of tariffs so far. They might even respond by raising the price of one car to help pay for the tariff on another.
With so much constantly shifting, your best tool for understanding local price changes is the Kelley Blue Book Fair Purchase Price, which we calculate using recent transactions for that car in your area. We update each Fair Purchase Price weekly, showing you how tariffs and tariff anxiety are affecting the prices of the specific vehicles you’re shopping for where you live.
Loan Conditions Continue to Improve
Prices are all that cash buyers need to worry about. However, few car shoppers pay cash. Most Americans borrow money to buy a new car.
On that front, the news is good — if you’re careful. In August, we saw the most permissive credit market since 2015.
Most Americans buy cars on credit, and the good news for August is that lenders approved almost three-quarters of applications. They asked for an average down payment of just 13%.
There are, however, warning signs in the data — nearly six in 10 buyers now fold some negative equity from an old loan into their new loan. Nearly a third of new loans stretch 72 months or longer — a move that lowers monthly payments but costs the borrower more in the long run. But qualifying is unlikely to get easier anytime soon.
Remember to shop for your loan based on its total cost, found on the Truth in Lending Disclosure included, by law, in every loan offer. A lower monthly payment isn’t worth it if it costs you significantly more in the long run.
Rates look increasingly likely to worsen soon, with most observers now expecting the Federal Reserve to raise its benchmark interest rate this fall.
What Used Car Shoppers Can Expect
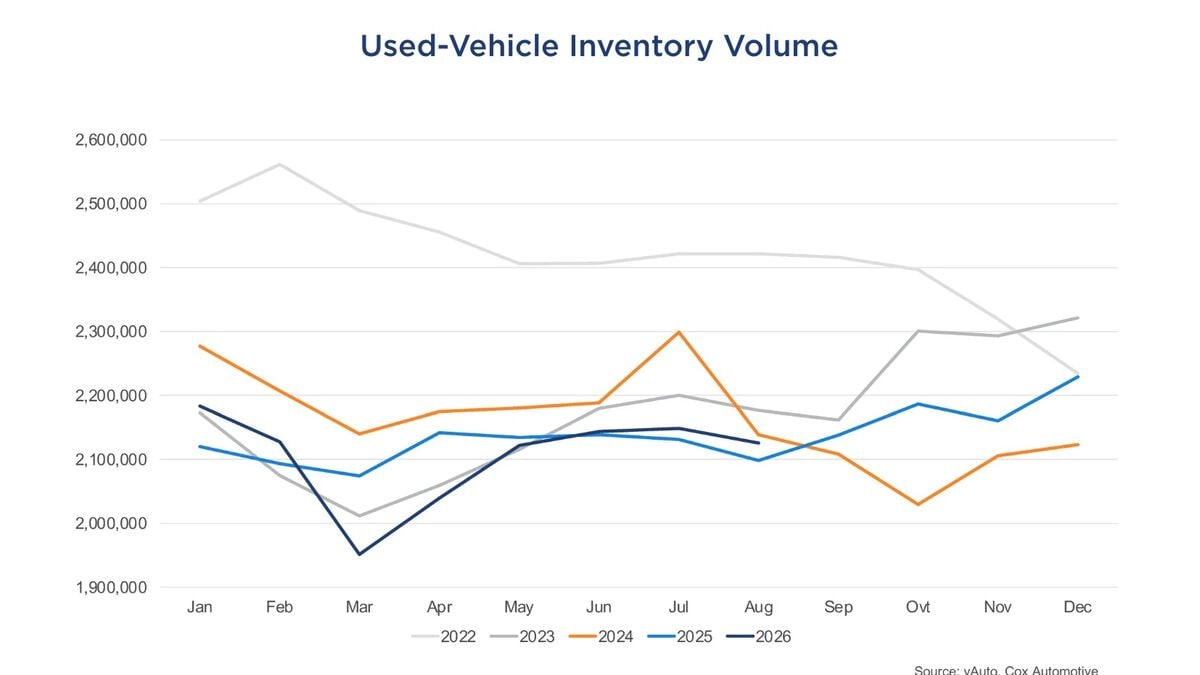
The average used car sold for $27,239 in August — the highest price we’ve seen since December 2022.
Prices may rise further in early fall. Dealers have a 44-day supply of used cars on average — down from midsummer highs.
Long-term trends are working against the used car shopper.
Americans are holding onto their cars much longer, and automakers have been producing fewer cars for several years. That means fewer used cars are available and prices are higher for the units sitting on dealers’ lots.
MORE: 1926: The Used Car Market Got a Pricing Foundation
Older, Less Expensive Cars Are Harder to Find
If you hope to find an older vehicle and your budget is less than $15,000, expect limited selection. Dealers have few such vehicles in stock.
The tariff threat could also push used car prices higher. When new car prices rise, would-be new car shoppers head to used lots looking for something still in their price range. That additional demand draws down used vehicle inventory. Plus, Americans are holding onto their cars longer than ever. The average vehicle on American roads is 12.8 years old. Automakers also produced fewer cars for several years after the 2008 recession, leaving fewer higher-mileage, older vehicles available for sale.
Once again, Ford, Chevrolet, Toyota, Honda, and Nissan were the top-selling brands, accounting for nearly 50% of all used vehicles sold.
Automakers Build More Expensive Cars
If you haven’t been car shopping in a while, the cars available may surprise you.
In recent years, inexpensive cars have grown scarce. Sales of vehicles priced at $25,000 or less have fallen by 78% in just five years. Six years ago, automakers offered 36 new models in that price range. Today? Four.
At the other end of the scale, they built 61 models priced at $60,000 or more in 2017. This year, they offer 114.
Dealers are pushing back, telling automakers they need more mainstream cars to sell, but correcting the problem will take time.
How to Buy a Car Right Now
New car prices remain about $8,000 higher than five years ago, before the COVID-19 pandemic. That’s when the average transaction price for new vehicles was just under $41,000. However, with all the technological advances and offerings, your next car will likely last longer and help you drive safer than ever.
RELATED: Buying Older, Used Cars in 2026
Vehicle quality studies repeatedly show that today’s new cars suffer fewer problems than those from just a few years earlier. Buyers of higher-priced used cars will likely see those vehicles stay on the road even longer. The same goes for those buying new ones.
With most automakers now building such durable cars, they compete by adding more high-tech features. Features like adaptive cruise control and Apple CarPlay are now more common than ever on entry-level vehicles. Read on for our tips on buying a car right now.
How to Leverage Incentives to Buy a New Car
Last month, incentives comprised about 6.5% of the average deal. To learn how to take advantage of incentives, read about our monthly best car deals for dealer or manufacturer offers, including cash back and lower interest rates when financing your next vehicle.
RELATED: How to Buy a New Car in 10 Steps
Selling a Car Right Now
Few of us can sell a car without needing to buy a replacement. If you can sell now, what are you waiting for? You could get more for your vehicle if it’s in high demand, and that’s excellent news. The best way to get the most money for your used car is to sell it privately. But if you don’t want the hassle, there is still an opportunity to sell to a dealership.
PRO TIP: If you’re selling a car, consider selling it peer-to-peer using Kelley Blue Book’s Private Seller Exchange marketplace. It’s a low-cost method that can help consumers get more for their vehicles than they might receive when selling to a dealership.
Trading in a Car Right Now
The ongoing shortage of used cars will be with us for years. As a result, you’ll likely still see respectable offers for your used car this month.
Shopping around for a decent price for your trade-in is still a good idea. Each dealership tries to keep a balance of vehicles on its lot. Sometimes, the one you want to buy from doesn’t need your trade-in desperately, but a competitor does.
Research your vehicle’s Kelley Blue Book value, then call several local dealerships to see what they’ll offer you for it. Or try our Instant Cash Offer tool, which brings you deals from various dealerships without obligation. You can choose your preferred offer or use it to negotiate with others.
Is Trading in Your Vehicle a Good Idea?
Possibly. You could get more money than usual if your vehicle is in high demand. That can help defray the costs of buying a new or used car. However, if your vehicle is not in high demand, you can expect to get close to the Kelley Blue Book value. Use Kelley Blue Book’s car valuation tool to find out the value of your current car.
Can You Trade in a Vehicle That’s Not Paid Off?
Yes. Whether you have paid off your car or not, you can still trade it in. However, a car depreciates when you drive it out of the dealership. It’s best to take stock of how much equity you carry in the vehicle. Take the difference between the car’s current market value and what you owe to figure that out. Read our story on selling a car.
Looking Ahead
New car tend to rise in late summer and early fall as cars from the next model year start to appear on dealer lots. Automakers will eventually have to address the yawning gap at the low-cost end of the car market. But they’re being conservative with their business decisions now, with few willing to take the risk of designing cheaper cars when the expensive ones are selling so well.
Used car prices, barring any unusual disruptions to the market, should increase only slightly.
If you need a new car soon, it might make sense to act now before interest rates rise.
RELATED: 10 Best Used Car Deals
Tips for Buying a Vehicle Right Now
If you shop right now, we recommend a few strategies to help you find the right new or used car that fits your budget.
- Expand your search. Widen your search to a broader geographic area because you could find a better deal or the used car you want outside your immediate area.
- Stay patient. Call dealerships to see what’s in stock for those high-demand vehicles. Leave a refundable deposit if you want first dibs.
- Buy a less expensive model. With higher car loan interest rates, consider buying a cheaper model instead of a more expensive one in the lineup you’re considering. Understand how much you can afford.
- Look for deals. Make sure to research car deals to find what works best for you. It may involve contacting or visiting several dealerships as you search for the right fit.
- Weigh your options. Don’t just look for a car; search for the best interest rates from banks or credit unions. Also, shop for insurance rates before the deal to know what it will cost to insure your desired vehicle. Then, weigh all your options, including financing incentives and deals at the dealership, if that’s where you buy your next vehicle. You may also find that the prices of some newer-model used vehicles are almost the same as those of new cars. Keep all your options open during your search.
- Avoid dealer markups. If you see a markup (sometimes called a “market adjustment”) on your final invoice, ask the dealer to remove it. If they refuse, shop at another dealership. Markups were more prevalent during the COVID-19 pandemic. However, dealers still mark up some vehicles that are in short supply.
- Question all add-ons. If your sales summary includes entries like “window tint,” “fabric protection,” “carpeted floor mats,” and other add-ons you didn’t request, ask the dealer to remove those line items from your invoice. Many dealers tack on these extras to make quick profits.
It may make more sense to keep your existing car for another year or two. If you must buy, be prepared to take excellent care of your next car to keep it running for a long time. Visit our Car Affordability Information Center for curated articles to help you make smart, budget-friendly decisions.
Editor’s Note: We have updated this article since its initial publication.